The cost of waiting on a Nassau County foreclosure
People assume the danger point in a foreclosure is the sale date. Financially, the damage is done gradually long before then.
By the time a Hicksville foreclosure reaches its final stages, the payoff can be materially higher than the original balance, and the difference comes straight out of what would have been yours. Selling earlier in the foreclosure is how that money gets protected.
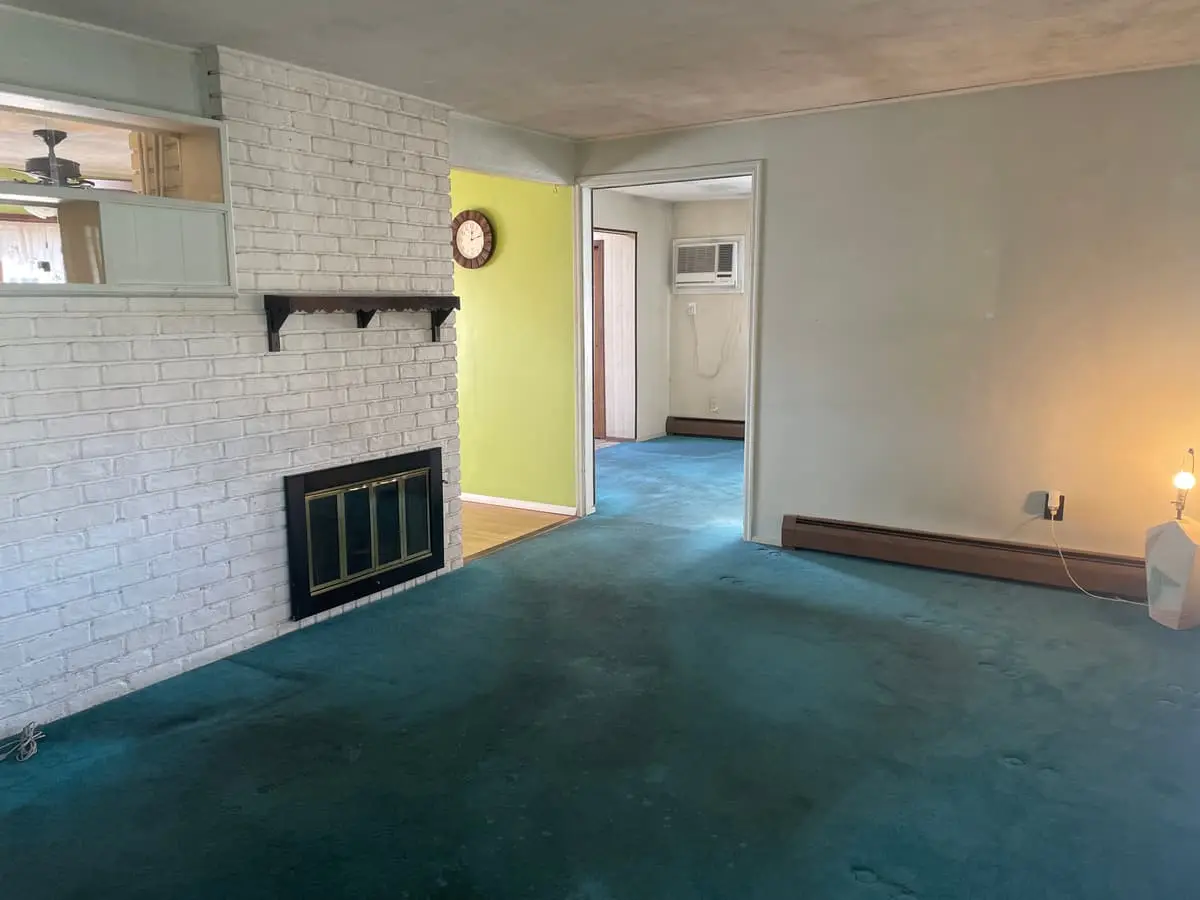
How we help Hicksville homeowners facing foreclosure
Most people arriving here have had one conversation with the servicer and come away more confused than before. What we can offer first is somebody who has been through this many times telling you plainly what stage you are at and what usually happens next.
If the numbers work, we buy the house and the foreclosure ends at closing. If you are underwater, we have worked a great many short sales and can walk that route with you instead. If the right answer is a modification, we will put you in front of a housing counselor we trust. All three are real outcomes and none of them costs you anything to explore.
What an agreement to purchase does to the timeline
People assume a scheduled foreclosure sale is the end of the conversation. Frequently it is not.
With a signed agreement in hand, your attorney has something concrete to bring to the lender, and adjournments do get granted on that basis. We cannot promise the outcome because it is not our decision. What we can do is be the buyer who signs quickly and does not fall through, which is the whole of what makes such a request credible in a Hicksville case.
The Hicksville market underneath this
The Hicksville median has barely moved year over year as of 2026-10, at 3%. Flat is the hardest market to price a fixer into, because there is no upward drift to cover a mistake and no urgency pushing buyers to overlook a problem. A $751,865 median puts Hicksville in the band where buyers are stretching to afford the house and have nothing left for the roof. That is precisely the buyer who walks away from a property needing work, and it is why condition matters more here than the price alone suggests. The median house here goes under contract in about 33 days, which is quick for Long Island. It is also a figure that only applies to property in showable condition.
Hicksville is roughly 43,869 people in Nassau County, ZIP 11801, and the housing stock is mostly cape cod, ranch, hi-ranch. Around Broadway and Old Country Road, most of it is old enough that the mechanicals are on their second or third life. The Hicksville stop pulls buyers who commute, which supports the good houses and does very little for the ones that need a roof. We have been buying across Nassau County for 15+ years. We know what the Hicksville Union Free School District does to a resale price, which blocks still have oil tanks in the ground, and what a house like yours is actually worth here.
If you owe more than the Hicksville house is worth
Being underwater is not the dead end people assume. It changes the route rather than closing it.
A short sale needs the lender's agreement to take less than they are owed, supported by a hardship package and a credible buyer. We have been through enough of them that the pattern is familiar: they take months, they need somebody who will not walk away partway, and they succeed far more often when the buyer has done one before.
Keeping a Hicksville foreclosure private
The part of foreclosure people dread is rarely the paperwork. It is somebody they know finding out.
A sale to us involves one person visiting once. No sign, no listing, no open house, no strangers walking through your home on a Sunday while you make yourself scarce.
What the two paths cost in Hicksville
These are the two routes open to you with a house in foreclosure, priced against what Hicksville houses actually sell for.
Work it against Hicksville's own numbers. The median sale here is $751,865. A 5% commission on that is $37,593, and seller closing costs of about 2% add roughly $15,037. Those are costs we can cover on our side. That is $52,631 gone before anyone counts the repairs it took to get the house listable.
There are two waits in a listed sale and people usually only count the first. In Hicksville the median house takes about 33 days to go from listed to a signed contract. Then it waits again, typically 45 to 60 days, while the buyer's lender orders an appraisal and underwrites the loan. Call it 78 to 93 days from sign to keys, assuming nothing goes wrong.
The part worth understanding is what a signed contract actually guarantees, which is less than most sellers assume. A retail buyer with a mortgage contingency can walk away right up to the end. If they do not qualify, if the appraisal comes in under the price, if they change their mind and let the financing lapse. A share of deals die exactly there, after months of waiting, and the house goes back on the market with time on it. We are not borrowing anything, so there is no lender to satisfy, no appraisal to come in low and no contingency to exercise.
| Listing with an agent | Selling to us | |
|---|---|---|
| Sale price | $751,865 (Hicksville median) | Our written offer |
| Commission | −$37,593 | None |
| Seller closing costs | −$15,037 | We can cover them |
| Repairs before listing | Out of pocket | None |
| Cleanout | Yours | Ours |
| Showings | Until it sells | One visit |
| Listed to signed contract | 33 days (Hicksville median, once listable) | 24 hours to a written offer |
| Contract to closing | 45 to 60 days (waiting on the buyer's lender) | A date you choose |
| Total wait | 78 to 93 days if nothing falls through | Yours to set |
| Can the buyer walk? | Yes (mortgage contingency runs to the end) | No financing to fall through |
| Before repairs and carrying | $699,234 | The number we put in writing |
The listing column assumes a 5% commission and seller closing costs of about 2%. Both vary. We have not subtracted repairs or the cost of carrying the house while it sits, because those depend on the property. A house in good condition listed with a good agent can absolutely beat a cash offer, and we will say so if that is your situation.
Where the money actually goes
Owners often assume a foreclosure wipes out their equity automatically. It does not, but the foreclosure process does consume it steadily, and an auction is rarely the venue where a house achieves its best price.
A sale you control, before the foreclosure completes, is the version where the equity is most likely to reach you rather than fund the costs of getting there.
Common questions
Is it too late to stop a Hicksville foreclosure once a sale date is set?
Not automatically, but the window is narrow once a foreclosure sale date exists and it depends on the specifics. Call as early as you can, and speak to an attorney at the same time.
Will I get any money out of a Hicksville foreclosure sale?
Only if the house is worth more than the total foreclosure payoff. Get the written payoff figure from the servicer first - it is the number that decides this, and everything else is guesswork until you have it.
Does selling my Hicksville house stop the foreclosure completely?
A sale that pays the mortgage off ends the foreclosure, yes. What it does to your credit record is a separate question and one worth asking an attorney or a credit counselor about.
Can you buy a Hicksville house once the foreclosure case has been filed?
Yes. A filed foreclosure does not prevent a sale in Hicksville, it simply adds a clock and some coordination between the attorneys. Tell us where the case stands and we will be straight with you about whether the timing works.